Weekly Outlook
What Happened This Week?
Global Markets
● The global economy is becoming increasingly dependent on U.S. investment in AI infrastructure, particularly data centres, to sustain growth amid the energy shock caused by the war in Iran. A slowdown in AI spending could therefore hit export-oriented economies particularly hard, especially those with limited alternative sources of growth.
● Rising energy prices and persistent inflation are increasing pressure on central banks to maintain or tighten monetary policy. However, policymakers remain divided over how quickly borrowing costs should rise without unnecessarily weakening economic activity.
● Anthropic stock is expected to hit the market on Thursday, November 19, 2026.
United States
● U.S. consumer inflation remained stronger than expected in October. The CPI increased 0.4% month on month, slowing from September’s 0.6% rise but exceeding economists’ forecasts of 0.3%. The Labor Department did not publish an annual inflation rate because data collection was disrupted by last year's government shutdown.
● Underlying price pressures have accelerated, with core consumer prices rising at an annualized pace of 3.7% over the three months through October, compared with 1.6% over the three months through July. The latest figures have strengthened expectations of another Fed rate increase in December, with markets pricing in an approximately 85% probability.
● Fed officials are increasingly debating the pace of further tightening. Governor Christopher Waller suggested that a 50-basis-point increase could be justified in December if inflation remains elevated, while Dallas Fed President Lorie Logan indicated that rates may need to rise more quickly. Governor Michelle Bowman also warned that October’s inflation figures point to persistent price pressures.
● Other policymakers favour a more measured approach. Philadelphia Fed President Anna Paulson supports gradual increases to give the economy time to adjust, unless inflation expectations, wage growth or underlying price pressures accelerate. Richmond Fed President Tom Barkin similarly urged caution, despite viewing the direction of policy as relatively clear given strong demand and elevated inflation.
● New York Fed President John Williams said monetary policy still has further ground to cover, pointing to a resilient economy, a strengthening labour market and inflation that remains too high.
● The potential impact of AI on the economy is also complicating the Fed's outlook. Barkin warned that an AI boom that significantly exceeds or falls short of expectations could reshape demand and employment, shifting the central bank's focus towards its maximum-employment mandate.
● Existing home sales fell in October to their lowest level since 2010 as mortgage rates climbed above 7%, highlighting the growing affordability pressures facing buyers.
● Small-business sentiment remained subdued. The NFIB optimism index edged down 0.1 points to 97.8 in October, staying below its 53-year average. However, the uncertainty index fell six points to 84, its lowest reading since December.
● Initial jobless claims increased to 200,000 in the week through November 7, slightly above expectations of 195,000. Continuing claims moved lower, declining by 20,000 to just under 1.7 million in the week through October 31.
● President Donald Trump said the U.S. did not need an agreement with Iran, raising concerns about a prolonged conflict. Oil prices moved higher, adding to inflation risks and reinforcing expectations of further Fed tightening.
United Kingdom
● The U.K. economy expanded 0.7% in the third quarter, its strongest quarterly growth since early 2024. The Bank of England estimates that AI-related demand has contributed just under one-fifth of economic growth since the beginning of 2026.
● The Bank of England raised interest rates last week for the first time since the outbreak of the U.S.-Iran war, as policymakers respond to persistent inflation risks and elevated energy costs.
● Deputy Governor Clare Lombardelli indicated that another increase could follow in the near term unless incoming data show a meaningful easing in inflationary pressures.
● The National Institute of Economic and Social Research believes the Bank may need to raise its key rate towards 5% to bring inflation under control. It forecasts that annual inflation could peak at 4.4% in February as energy costs remain elevated. Although such a move could bring inflation back to target around 18 months earlier, it would also weigh on economic growth in 2028 and 2029.
● The Bank of England has pushed back against market expectations that its policy rate will reach 5% from the current 4% by the end of next year, suggesting that investors may be anticipating a more aggressive tightening cycle than policymakers consider necessary.
Canada
● Minutes from the Bank of Canada's late-October meeting showed that policymakers agreed to raise the benchmark rate to 2.5% to address the risk of inflation remaining higher than expected. Officials highlighted uncertainty surrounding U.S.-Canada trade relations, the war in Iran and the speed at which businesses are passing higher costs on to consumers.
● Governor Tiff Macklem has stressed that further increases will be approached cautiously, with geopolitical developments and trade tensions making the economic outlook particularly difficult to assess.
● More recent signs of weaker growth and job losses have prompted traders to reduce expectations of another rate increase in December.
Japan
● Japan reportedly spent a record $50 billion in a single day on July 30 to support the yen, according to Ministry of Finance data. Finance Minister Satsuki Katayama and U.S. Treasury Secretary Scott Bessent confirmed that the two countries coordinated intervention efforts.
● Stronger-than-expected U.S. inflation has widened the interest-rate differential between the U.S. and Japan, putting renewed pressure on the yen. Analysts believe the Bank of Japan may need to raise borrowing costs further to limit currency weakness.
● However, Bank of Japan board member Toichiro Asada urged policymakers to proceed carefully, warning that premature tightening could undermine economic growth. He argued that the central bank should first establish that wage increases are generating stronger domestic demand and sustained inflation.
China
● The People's Bank of China reiterated its commitment to supporting economic growth but also expressed concern about keeping interest rates too low. Analysts believe the current easing cycle may be nearing its end, with further monetary support potentially delayed until next year and implemented gradually.
Singapore
● The Monetary Authority of Singapore is developing gold-vaulting services to strengthen the city-state's position as a major Asian gold-trading centre. The initiative will allow foreign central banks, international institutions and sovereign entities to store gold reserves in Singapore.
● Singapore also expects its over-the-counter gold-clearing system to begin live operations in the first quarter of 2027, supporting its ambition to expand its role in international bullion markets.
This Week’s Market Movers
Forex
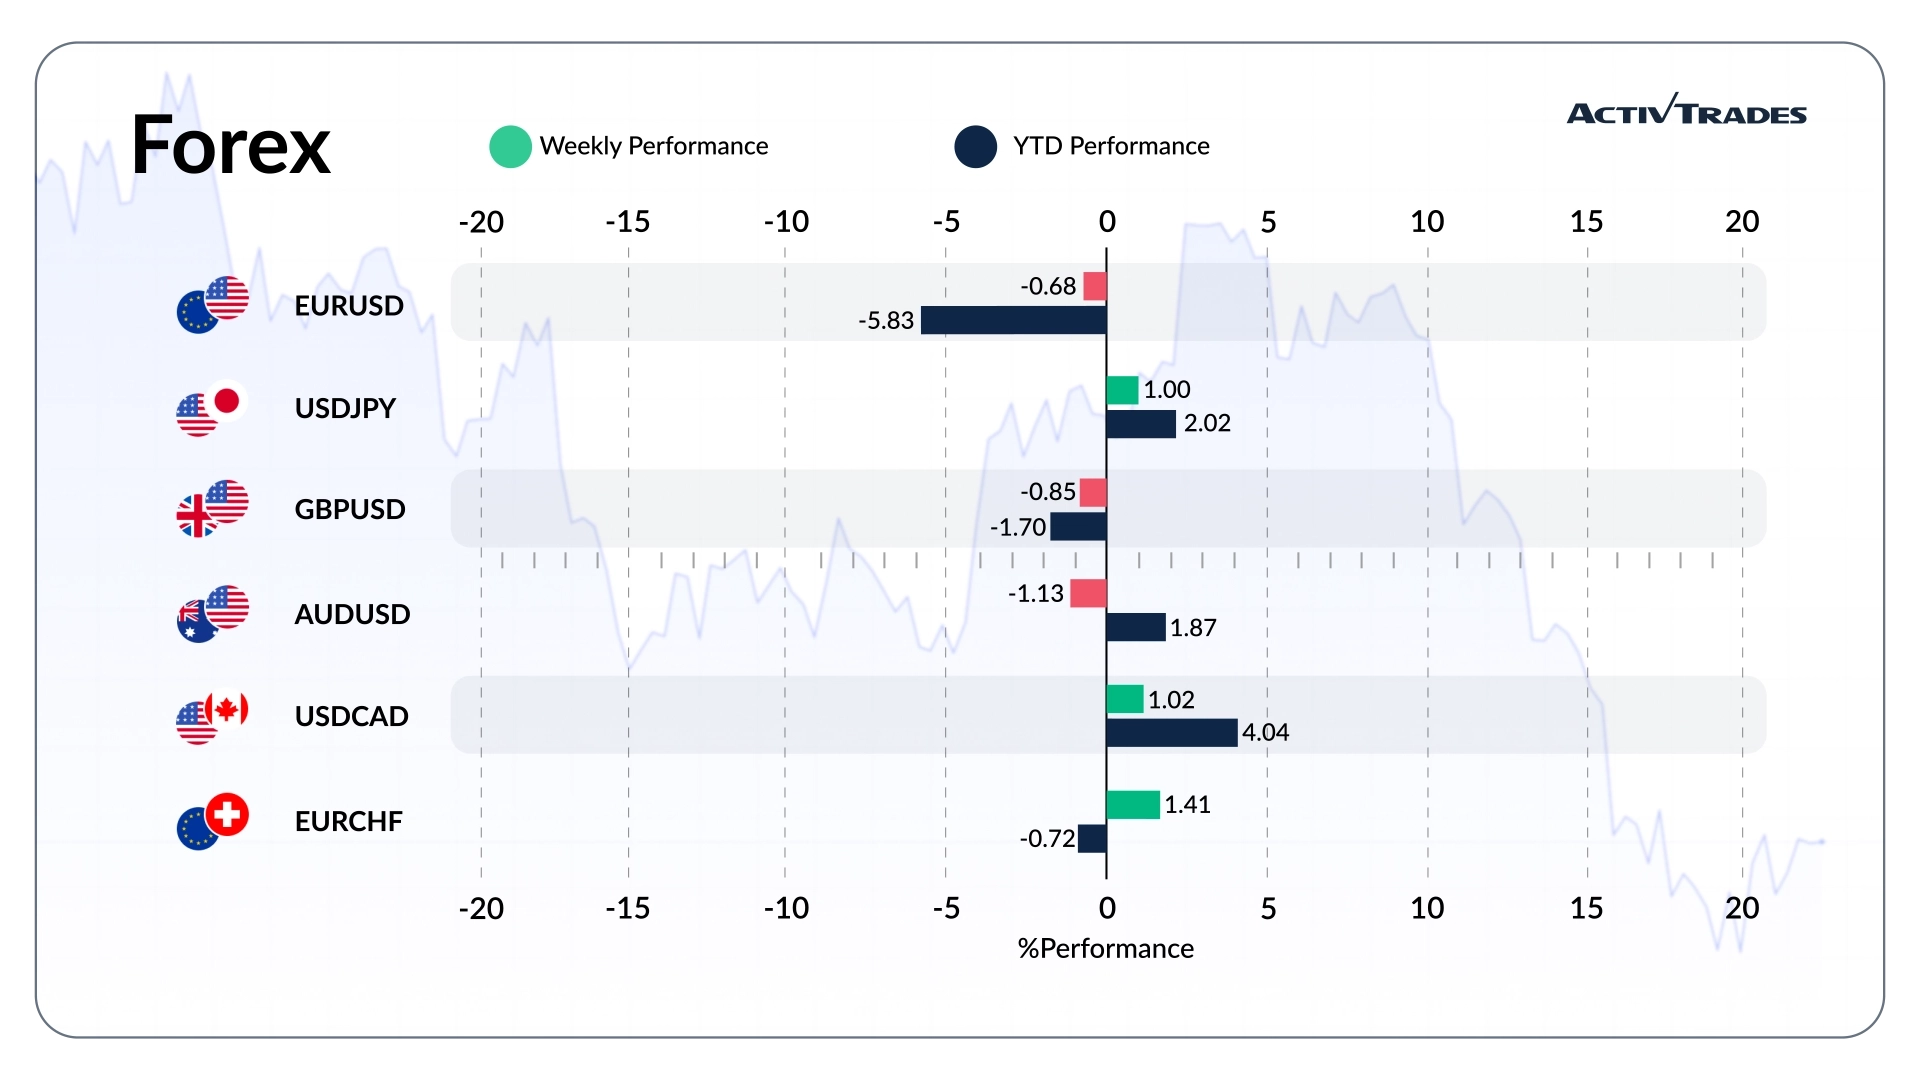
● The USD/NOK is up more than 2.8%.
● The USD/BRL is up more than 2.5%.
● The USD/CHF and the USD/SEK are up more than 2.2%.
● The USD/CAD is up more than 1.7%.
● The NZD/CHF is up more than 1.4%.
● The USD/JPY is up more than 1.3%.
● The JPY/CHF is up more than 1.1%.
● The EUR/MXN is down more than 2%.
● The CHF/HKD is down more than 2.2%.
● The AUD/USD is down more than 1.8%.
● The CHF/EUR is down more than 0.9%.
Commodities
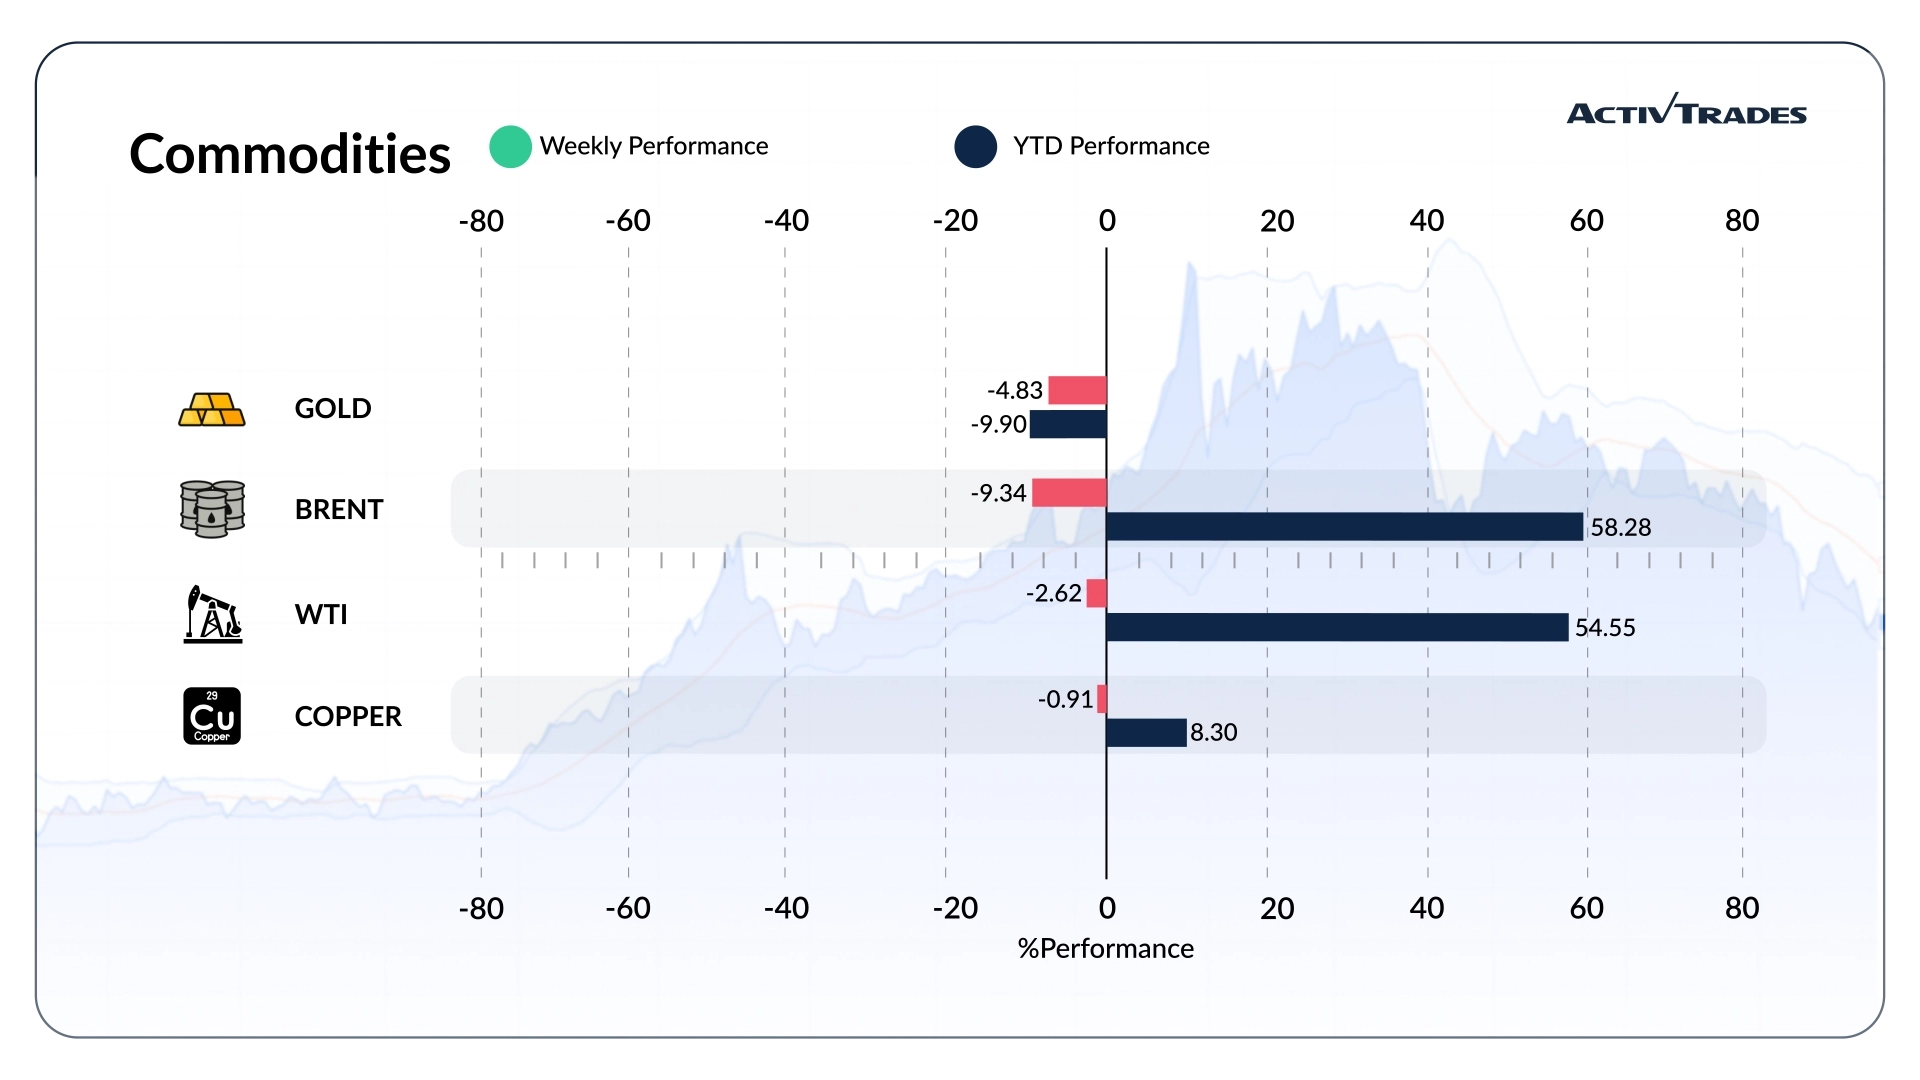
● Dutch TTF Natural Gas prices are up more than 11.6%.
● Oats and Natural Gas prices are up more than 9.8%.
● Orange Juice prices are up more than 5.6%.
● Gold prices are down more than 4.4%.
● Silver prices are down more than 3.9%.
Indices
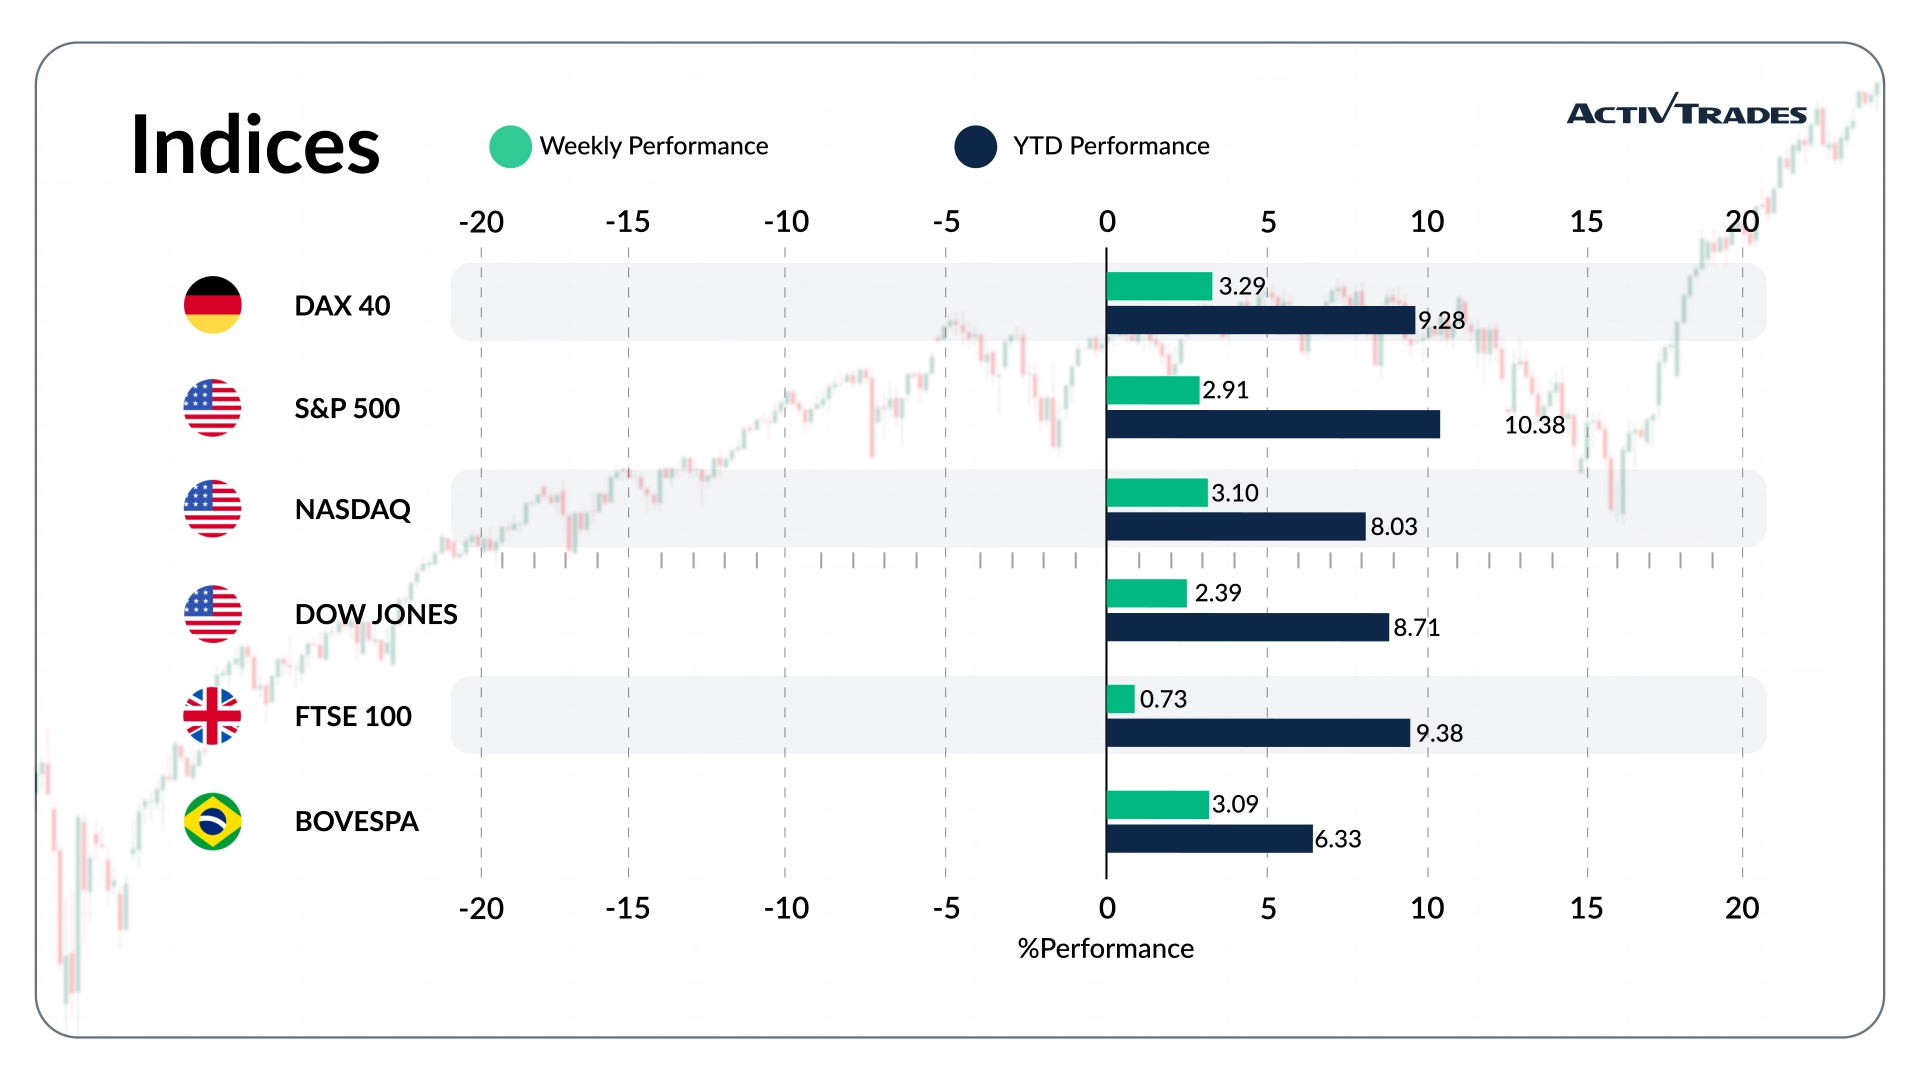
● The VIX index is up more than 9.10%.
● The IDX30 index is up more than 8.8%.
● The IDX Composite index is up more than 7%.
● The Dow Jones Industrial Average index is down more than 2.5%.
● The SP500 index is down more than 1%.
Shares
Tops
● AMD: +44.73%
● Rocket Lab: +39.31%
● Arista Networks: +29.83%
● Coreweave: +29.64%
● Monolithic Power Systems: +27.93%
● Ciena: +27.37%
● Astera Labs: +26.92%
● Lam Research: +26.23%
● Siemens: +16.41%
● STMicroelectronics: +14.23%
● Infineon Technologies: +13.41%
Flops
● Corteva: -23.67%
● Axon: -19.72%
● First Solar: -11.98%
● Strategy: -11.52%
● Davita: -10.65%
● Stellantis: -10.38%
● Brenntag: -10%
Important Events to Follow
Monday 16 November
● 02:00 AM - Chinese - Industrial Production YoY (October)
○ Previous: 5.5%
○ Forecast: 5.3%
● 02:00 AM - Chinese - Retail Sales YoY (October)
○ Previous: 1.1%
○ Forecast: 0.8%
● 01:30 PM - Canadian - Inflation Rate YoY (October)
○ Previous: 3.1%
○ Forecast: 3.2%
Tuesday 17 November
● 12:30 AM - Australian - RBA Meeting Minutes
● 07:00 AM - UK - Unemployment Rate (September)
○ Previous: 4.7%
○ Forecast: 4.9%
● 10:00 AM - German - ZEW Economic Sentiment Index (November)
○ Previous: 28.1
○ Forecast: 15.9
● 01:30 PM - American - Retail Sales MoM (October)
○ Previous: 0.8%
○ Forecast: 0%
● 11:50 PM - Japanese - Balance of Trade (October)
○ Previous: ¥-536.6B
○ Forecast: ¥-450.0B
Wednesday 18 November
● 7:00 AM - UK - Inflation Rate YoY (October)
○ Previous: 3.5%
○ Forecast: 3.5%
● 7:00 PM - American - FOMC Minutes
Thursday 19 November
● 11:30 PM - Japanese - Inflation Rate YoY (October)
○ Previous: 2.1%
○ Forecast: 2.9èmes %
Friday 20 November
● 07:00 AM - UK - Retail Sales MoM (October)
○ Previous: -0.4%
○ Forecast: 0.1%
Major Earnings Reports to Watch
Monday 16 November
● BAIDU
● Tyson Foods
Tuesday 17 November
● WALT DISNEY
● JD.com
● HOME DEPOT
● Weibo Corporation
● NVIDIA
● Alstom
Wednesday 18 November
● Sonae
● TJX Companies
● Lowe'S Cos
● Target
● EXPERIAN
Thursday 19 November
● WALMART
● Ubisoft Entertainment
Source: The Wall Street Journal, Investing, Trading Economics Calendar GMT, Reuters, TradingView and ActivTrades’ Data as of November 13, 2026
The information provided does not constitute investment research. The material has not been prepared in accordance with the legal requirements designed to promote the independence of investment research and as such is to be considered to be a marketing communication.
All information has been prepared by ActivTrades (“AT”). The information does not contain a record of AT’s prices, or an offer of or solicitation for a transaction in any financial instrument. No representation or warranty is given as to the accuracy or completeness of this information.
Any material provided does not have regard to the specific investment objective and financial situation of any person who may receive it. Past performance is not a reliable indicator of future performance. AT provides an execution-only service. Consequently, any person acting on the information provided does so at their own risk. Forecasts are not guarantees. Rates may change. Political risk is unpredictable. Central bank actions may vary. Platforms’ tools do not guarantee success.