
Weekly Outlook
What Happened This Week?
Global Markets
- The IMF forecasts global growth of 3.1% this year but warns that persistent inflation, rising borrowing costs and mounting public debt could trigger a sharp slowdown. Growth is increasingly dependent on a narrow set of technological and financial drivers, including the AI boom.
- The IMF cautioned advanced economies against excessive reliance on short-term debt, which leaves governments exposed to refinancing risks and higher borrowing costs. The U.S. relies more heavily on short-term Treasury bills than any other G7 economy, with federal interest payments projected to reach 5.7% of GDP by 2031, compared with 2.8% before the pandemic.
- U.S. economists Robert E. Hall and Michael Woodford won the Nobel Prize in Economic Sciences for research explaining why previous stabilization policies failed. Their work highlighted the importance of clear communication from governments and central banks to households and businesses.
United States
- Fed Chair Kevin Warsh declined to signal whether another rate hike is coming in October, saying the central bank no longer previews its policy decisions. The Fed raised rates last month to 3.75%–4%, its first increase in three years.
- Fed officials remain divided on the outlook. New York Fed President John Williams said another hike this year may be appropriate and left the door open to further increases in 2027, with AI-driven demand a key inflation risk. Vice Chair Michelle Bowman, however, sees no urgency to act and favours waiting to assess how financial conditions evolve.
- U.S. producer prices surged 1.3% in September, their largest monthly increase since March 2022. Annual producer-price inflation accelerated to 6.3%, its highest since December 2022, reinforcing concerns about persistent price pressures.
- Consumer inflation also came in above expectations, with September CPI rising 3.7% year on year versus the 3.6% forecast by economists.
- U.S. retail sales increased 0.8% in September to $745 billion, slowing from August’s 1.3% gain but comfortably exceeding expectations for 0.4%. Resilient consumer demand could give the Fed more reason to keep rates elevated.
- The Fed’s Beige Book indicated that economic activity continued to expand at a slight-to-moderate pace across most districts. Price pressures intensified in some areas, while businesses cited uncertainty over energy costs and tariffs and anticipated further price increases.
- Initial jobless claims rose to 199,000 in the week through October 10, ending five consecutive weeks of declines but remaining just below expectations of 200,000. Continuing claims fell by 4,000 to 1.71 million in the week through October 3.
Eurozone
- Eurozone industrial production fell 0.5% in August, marking a third consecutive monthly decline and missing expectations for a 0.2% increase. Economist Bert Colijn warned that elevated energy costs could put further pressure on output in the coming months.
- ECB policymaking remains data dependent, with officials monitoring the impact of higher energy prices and tighter financial conditions on economic activity.
France
- Bank of France Governor Emmanuel Moulin said monetary policy decisions will be made meeting by meeting as new data emerge. He noted that the recent surge in government bond yields is weighing on economic activity but expressed confidence that France can make substantial progress in reducing its budget deficit.
United Kingdom
- Bank of England Chief Economist Huw Pill questioned whether a full percentage point of rate increases would be necessary, arguing that clearer evidence of inflation risks would be needed to justify four consecutive 25-basis-point hikes. The Bank has held its key rate at 3.75% since December, although markets expect an increase to 4% in early November.
- The U.K. government faces growing fiscal pressure ahead of its October 28 budget, with rising bond yields and investor concerns about debt reduction. Public spending in the first five months of the fiscal year exceeded the Office for Budget Responsibility’s March forecast by £7.4 billion. The Institute for Fiscal Studies estimates the government may have around £20 billion of headroom against its fiscal targets.
Asia
- The IMF raised its 2026 growth forecast for Asia to 4.8% but expects expansion to slow to 4.4% in 2027. It warned that weak fiscal positions and uncertainty surrounding the AI boom pose risks, with any reversal in AI investment or valuations potentially hitting the region disproportionately hard.
- China is likely to qualify for the World Bank’s high-income category for 2026, although Beijing continues to identify with developing economies and the Global South. The World Bank does not formally classify countries as developed or developing and plans to phase out lending to China by 2031.
- China’s producer-price inflation accelerated to 5.0% year on year in September, up from 3.8% in August. Consumer inflation reached 0.9%, slightly below the 1.0% expected. Economists argue that stronger fiscal stimulus may be needed to sustain the return to rising prices.
- Singapore’s central bank unexpectedly left monetary policy unchanged, with the Monetary Authority of Singapore maintaining the existing pace of appreciation for the Singapore dollar’s nominal effective exchange rate policy band. Only one of 11 economists surveyed by The Wall Street Journal had anticipated the decision.
- Bank Indonesia is closely monitoring oil prices and the Federal Reserve ahead of its next policy meeting. Governor Destry Damayanti said the bank currently expects a Fed rate hike in December, while volatile oil prices remain a key downside risk for Indonesia’s economy.
- The Bank of Thailand sees room to maintain its accommodative stance at the current 1% policy rate, with Deputy Governor Piti Disyatat ruling out a clear case for a rate cut. The central bank also plans to substantially reduce its 2026 average inflation forecast from the 2.8% projected in June.
Canada
- Canadian building permits rebounded 8.8% in August to C$13.57 billion, driven by a 15.3% monthly increase in residential construction intentions to C$8.47 billion. Nonresidential permits edged down 0.6% to C$5.1 billion, reflecting weaker commercial construction plans.
This Week’s Market Movers
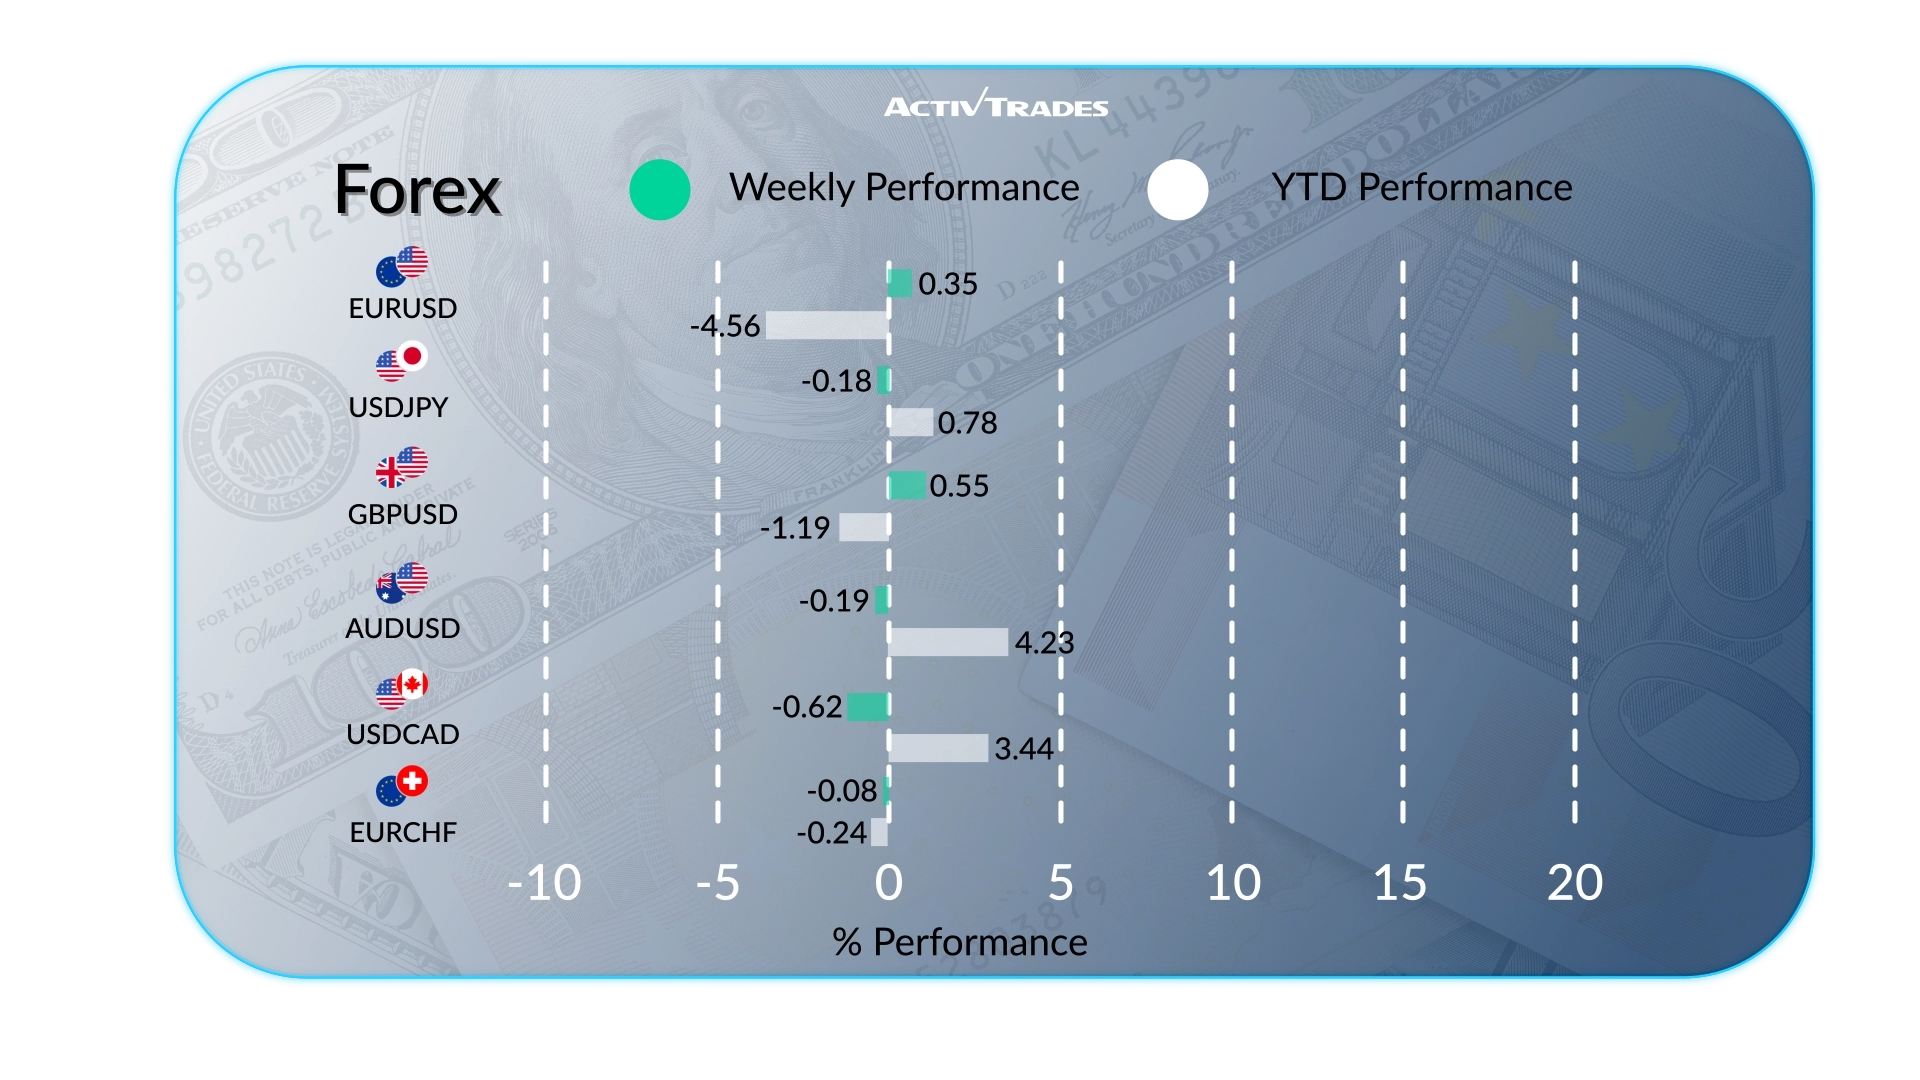
- The USD/BRL is up more than 1.6%.
- The EUR/MXN and the USD/MXN are up more than 1.4%.
- The NOK/JPY is up more than 1.3%.
- The NZD/AUD is up more than 1%.
- The NZD/JPY is up more than 0.9%.
- The NZD/USD is up more than 0.8%.
- The GBP/USD is up more than 0.5%.
- The USD/RUB is down more than 1.5%.
- The AUD/GBP is down more than 0.7%.
- The USD/CHF is down more than 0.5%.
Commodities
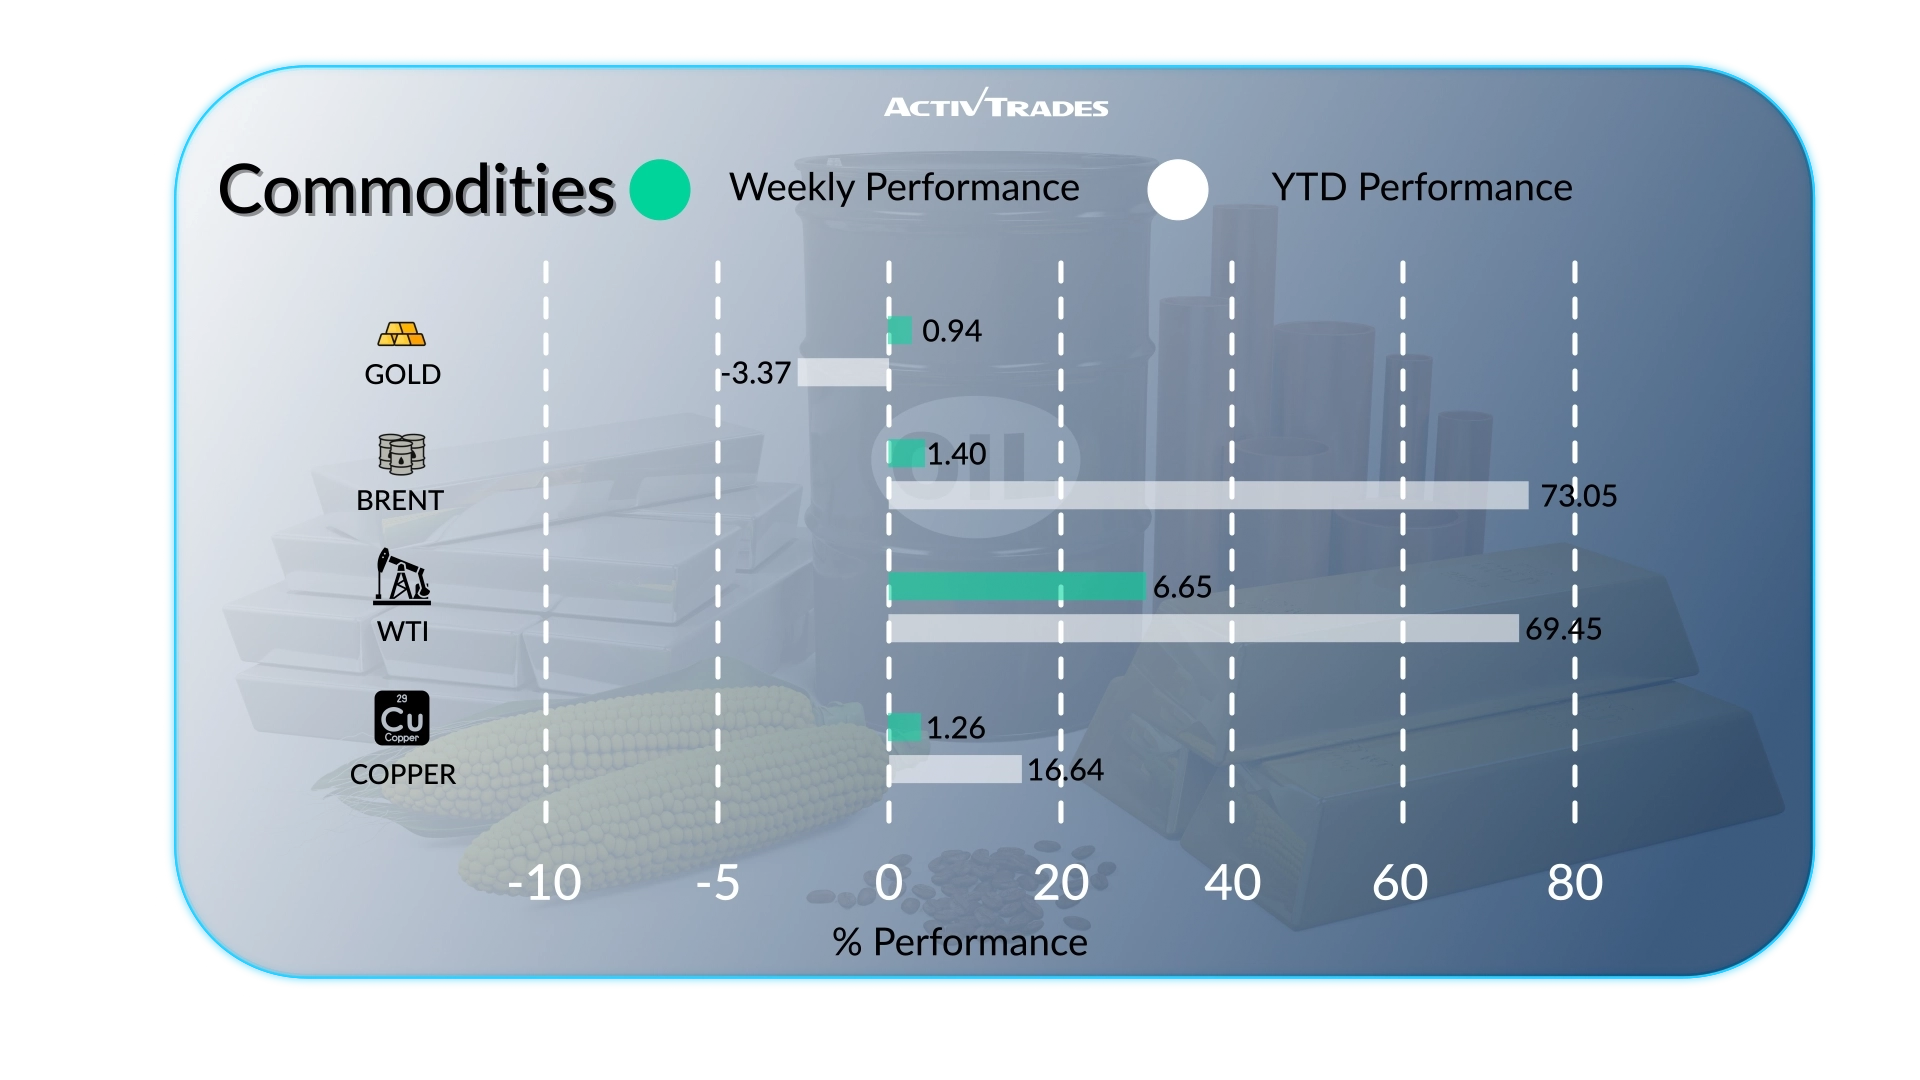
- Crude Oil WTI prices are up more than 9.9%.
- Sugar and Coffee prices are up more than 4%.
- Lean Hogs prices are down more than 11%.
- London Gas Oil and Silver prices are down more than 5%.
- Oats and Orange Juice prices are down more than 4%.
Indices
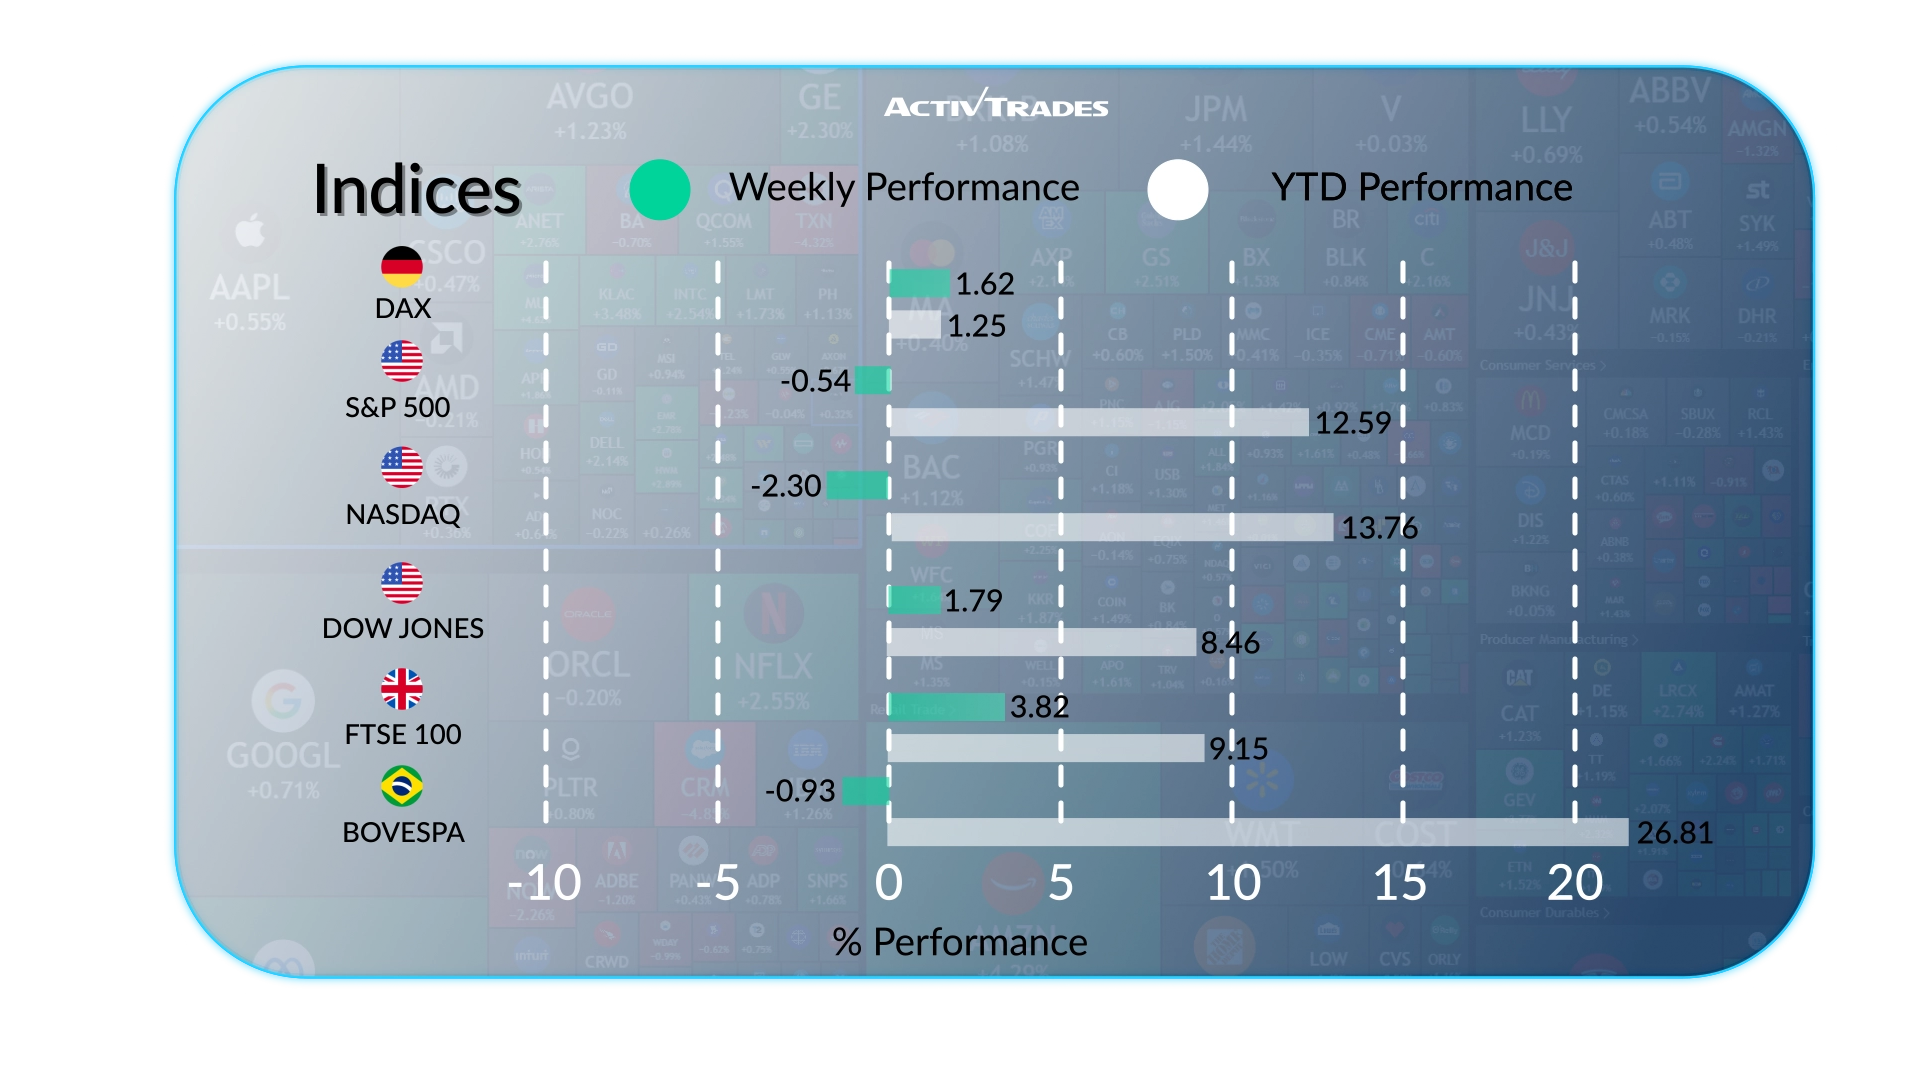
- The VIX index is up more than 4.9%.
- The UK100 index is up more than 3.6%.
- The Kospi index is down more than 15.7%.
- The IDX Composite index is down more than 13.3%.
- The IDX 30 index is down more than 12%.
Shares
Tops
- Moderna: +20.05%
- Crown Castle: +16.13%
- Estee Lauder: +13.65%
- Humana: +11.64%
- Scout24: +11.30%
- Equifax: +10.80%
- CDW: +10.33%
- Cap gemini: +10.15%
Flops
- Paramount Skydance: -21.77%
- Rocket Lab: -19.23%
- Dell Technologies: -17.61%
- Hewlett Packard: -17.42%
- Lumentum: -17.08%
- Ciena: -16.30%
- Applied Materials: -15.61%
- Coreweave: -14.57%
- STMicroelectronics: -13.70%
- Infineon Technologies: -10.92%
Important Events to Follow
Monday 19 October
- 02:00 AM - Chinese - GDP Growth Rate YoY (Q3)
- Previous: 4.3%
- Forecast: 4.4%
- 02:00 AM - Chinese - Industrial Production YoY (September)
- Previous: 5.2%
- Forecast: 4.8%
- 02:00 AM - Chinese - Retail Sales YoY (September)
- Previous: 0.4%
- Forecast: 1%
- 12:30 PM - Canadian - Inflation Rate YoY (September)
- Previous: 3%
- Forecast: 3.2%
Tuesday 20 October
- 06:00 AM - UK - Unemployment Rate (August)
- Previous: 4.9%
- Forecast: 4.9%
- 09:00 AM - German - ZEW Economic Sentiment Index (October)
- Previous: 34.7
- Forecast: 25.1
- 12:30 PM - American - Building Permits Prel (September)
- Previous: 1.403M
- Forecast: 1.39M
- 12:30 PM - American - Housing Starts (September)
- Previous: 1.275M
- Forecast: 1.3M
- 12:50 PM - Japanese - Balance of Trade (September)
- Previous: ¥-1105.6B
- Forecast: ¥ -250B
Wednesday 21 October
- 06:00 AM - UK - Inflation Rate YoY (September)
- Previous: 3.1%
- Forecast: 3.4%
Thursday 22 October
- 10:00 AM - Australian - S&P Global Manufacturing PMI Flash (October)
- Previous: 49.6
- Forecast: 49.4
- 10:00 AM - Australian - S&P Global Services PMI Flash (October)
- Previous: 51.9
- Forecast: 51.1
- 11:30 PM - Japanese - Inflation Rate YoY (September)
- Previous: 1.9%
- Forecast: 2.0%
Friday 23 October
- 12:30 PM - Japanese - S&P Global Manufacturing PMI Flash (October)
- Previous: 54.1
- Forecast: 43.8
- 12:30 PM - Japanese - S&P Global Services PMI Flash (October)
- Previous: 51.3
- Forecast: 51.3
- 06:00 AM - UK - Retail Sales MoM (September)
- Previous: 0.5%
- Forecast: 0.5%
- 07:15 AM - French - S&P Global Composite PMI Flash (October)
- Previous: 51.1
- Forecast: 50.1
- 07:15 AM - French - S&P Global Manufacturing PMI Flash (October)
- Previous: 50.6
- Forecast: 50.0
- 07:15 AM - French - S&P Global Services PMI Flash (October)
- Previous: 51.2
- Forecast: 50.2
- 07:30 AM - German - S&P Global Manufacturing PMI Flash (October)
- Previous: 53.9
- Forecast: 53.2
- 07:30 AM - German - S&P Global Composite PMI Flash (October)
- Previous: 53.8
- Forecast: 53
- 07:30 AM - German - S&P Global Services PMI Flash (October)
- Previous: 52.9
- Forecast: 52.5
- 08:00 AM - European - S&P Global Composite PMI Flash (October)
- Previous: 53.1
- Forecast: 52.3
- 08:00 AM - European - S&P Global Manufacturing PMI Flash (October)
- Previous: 52.9
- Forecast: 52.5
- 08:00 AM - European - S&P Global Services PMI Flash (October)
- Previous: 53.0
- Forecast: 52.2
- 08:30 AM - UK - S&P Global Manufacturing PMI Flash (October)
- Previous: 51.9
- Forecast: 51.8
- 08:30 AM - UK - S&P Global Services PMI Flash (October)
- Previous: 52.1
- Forecast: 51.9
- 01:45 PM - American - S&P Global Composite PMI Flash (October)
- Previous: 58.4
- Forecast: 57.6
- 01:45 PM - American - S&P Global Manufacturing PMI Flash (October)
- Previous: 55.9
- Forecast: 55
- 01:45 PM - American - S&P Global Services PMI Flash (October)
- Previous: 58.8
- Forecast: 58
Major Earnings Reports to Watch
Tuesday 20 October
- NETFLIX
- GENERAL ELECTRIC
- 3M
- Halliburton
- General Motors
- Raytheon Technology
- AMC
- UCB
- United Airlines
- Hasbro
Wednesday 21 October
- Abbott Lab
- TESLA MOTORS
- AT&T
- IBM
- Philip Morris
- Iberdrola
- SAP
Thursday 22 October
- Lockheed Martin
- Newmont Goldcorp
- American Airlines
- Union Pacific
- Nokia Corp
- BARCLAYS
- PROCTER & GAMBLE
Friday 23 October
- AMERICAN EXPRESS
- ENI
Source: The Wall Street Journal, Investing, Trading Economics Calendar GMT, Reuters, TradingView and ActivTrades’ Data as of October 16, 2026
The information provided does not constitute investment research. The material has not been prepared in accordance with the legal requirements designed to promote the independence of investment research and as such is to be considered to be a marketing communication.
All information has been prepared by ActivTrades (“AT”). The information does not contain a record of AT’s prices, or an offer of or solicitation for a transaction in any financial instrument. No representation or warranty is given as to the accuracy or completeness of this information.
Any material provided does not have regard to the specific investment objective and financial situation of any person who may receive it. Past performance is not a reliable indicator of future performance. AT provides an execution-only service. Consequently, any person acting on the information provided does so at their own risk. Forecasts are not guarantees. Rates may change. Political risk is unpredictable. Central bank actions may vary. Platforms’ tools do not guarantee success.